Blog

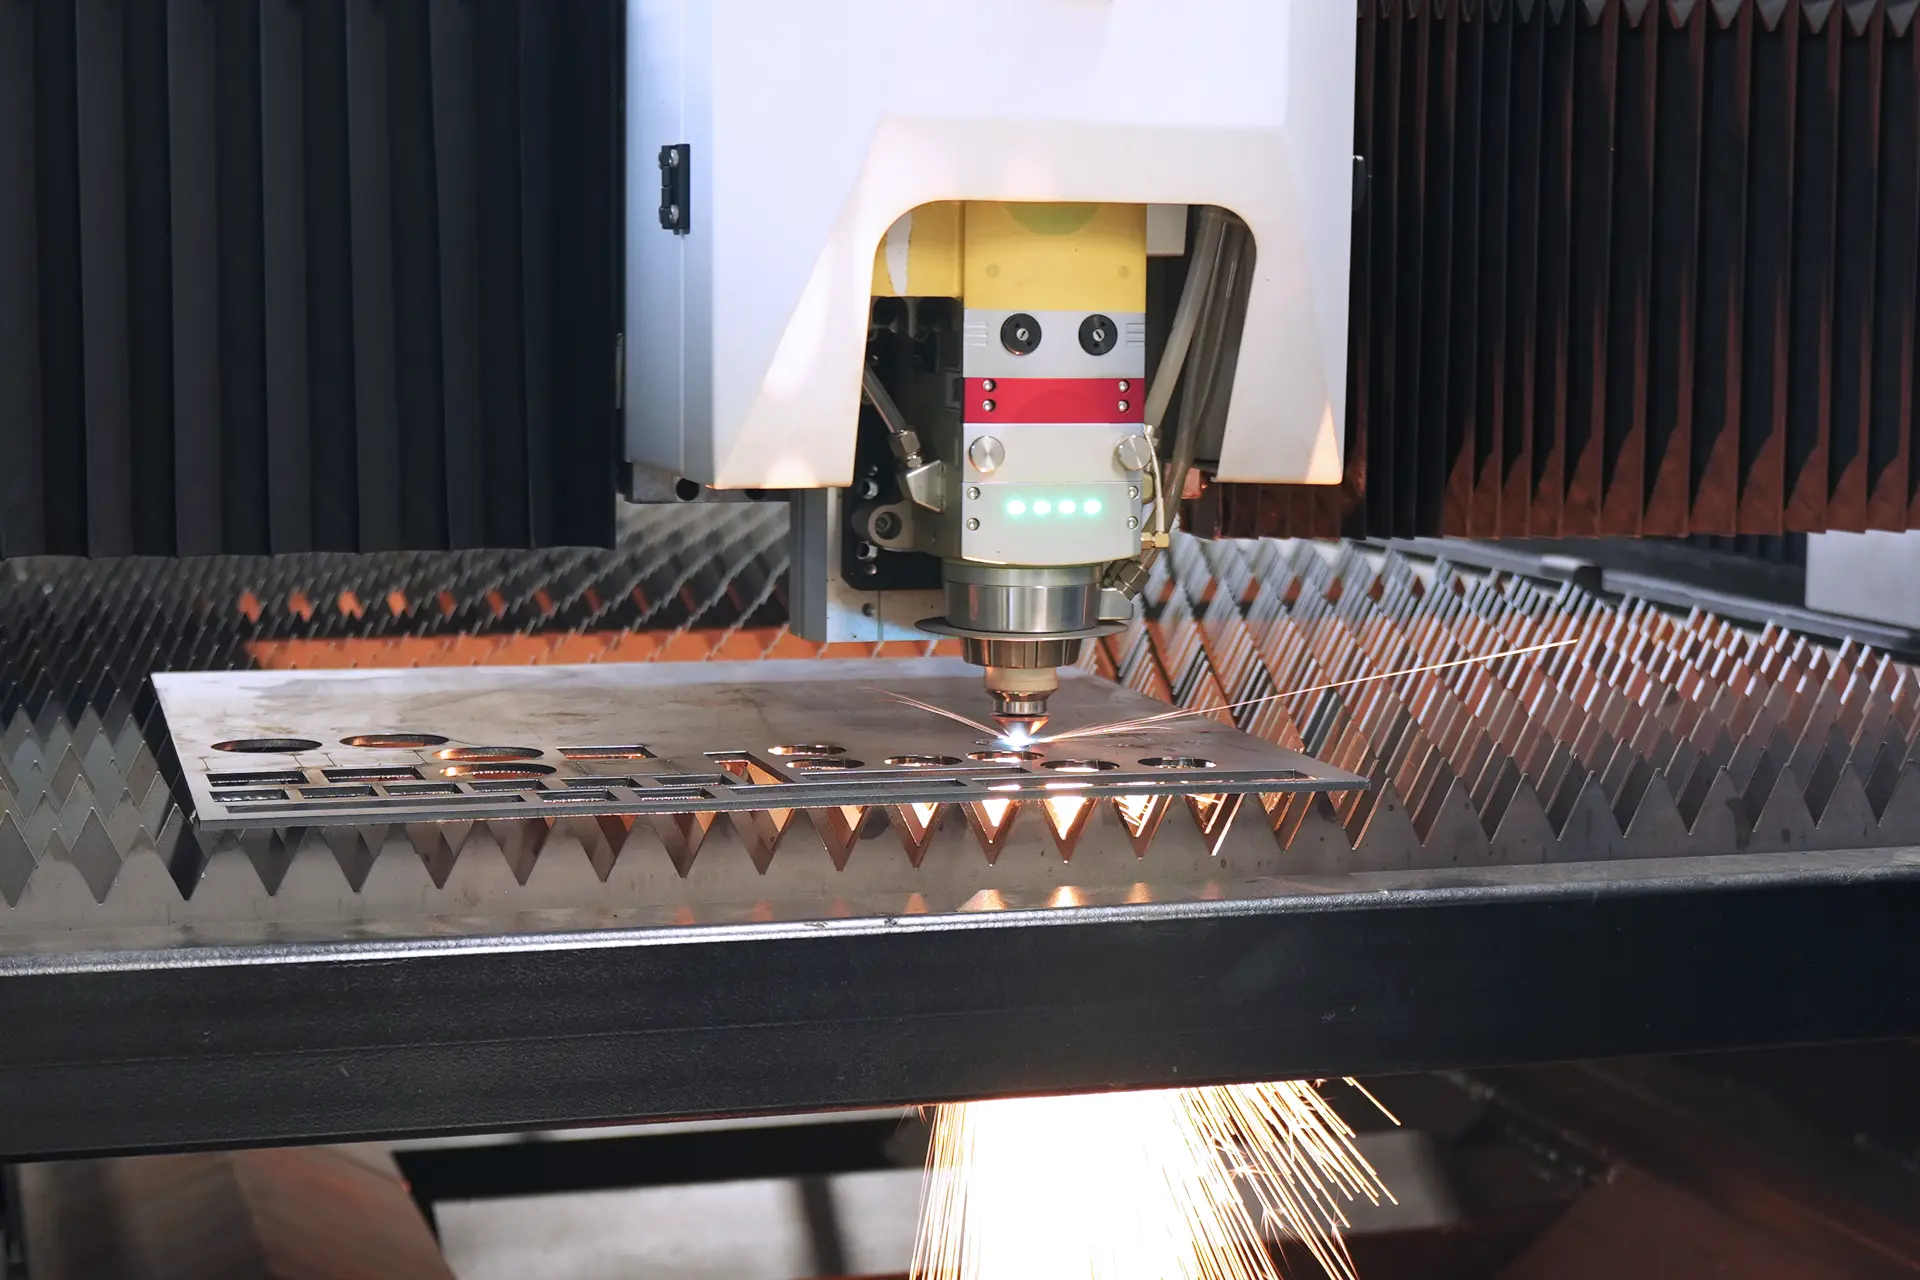
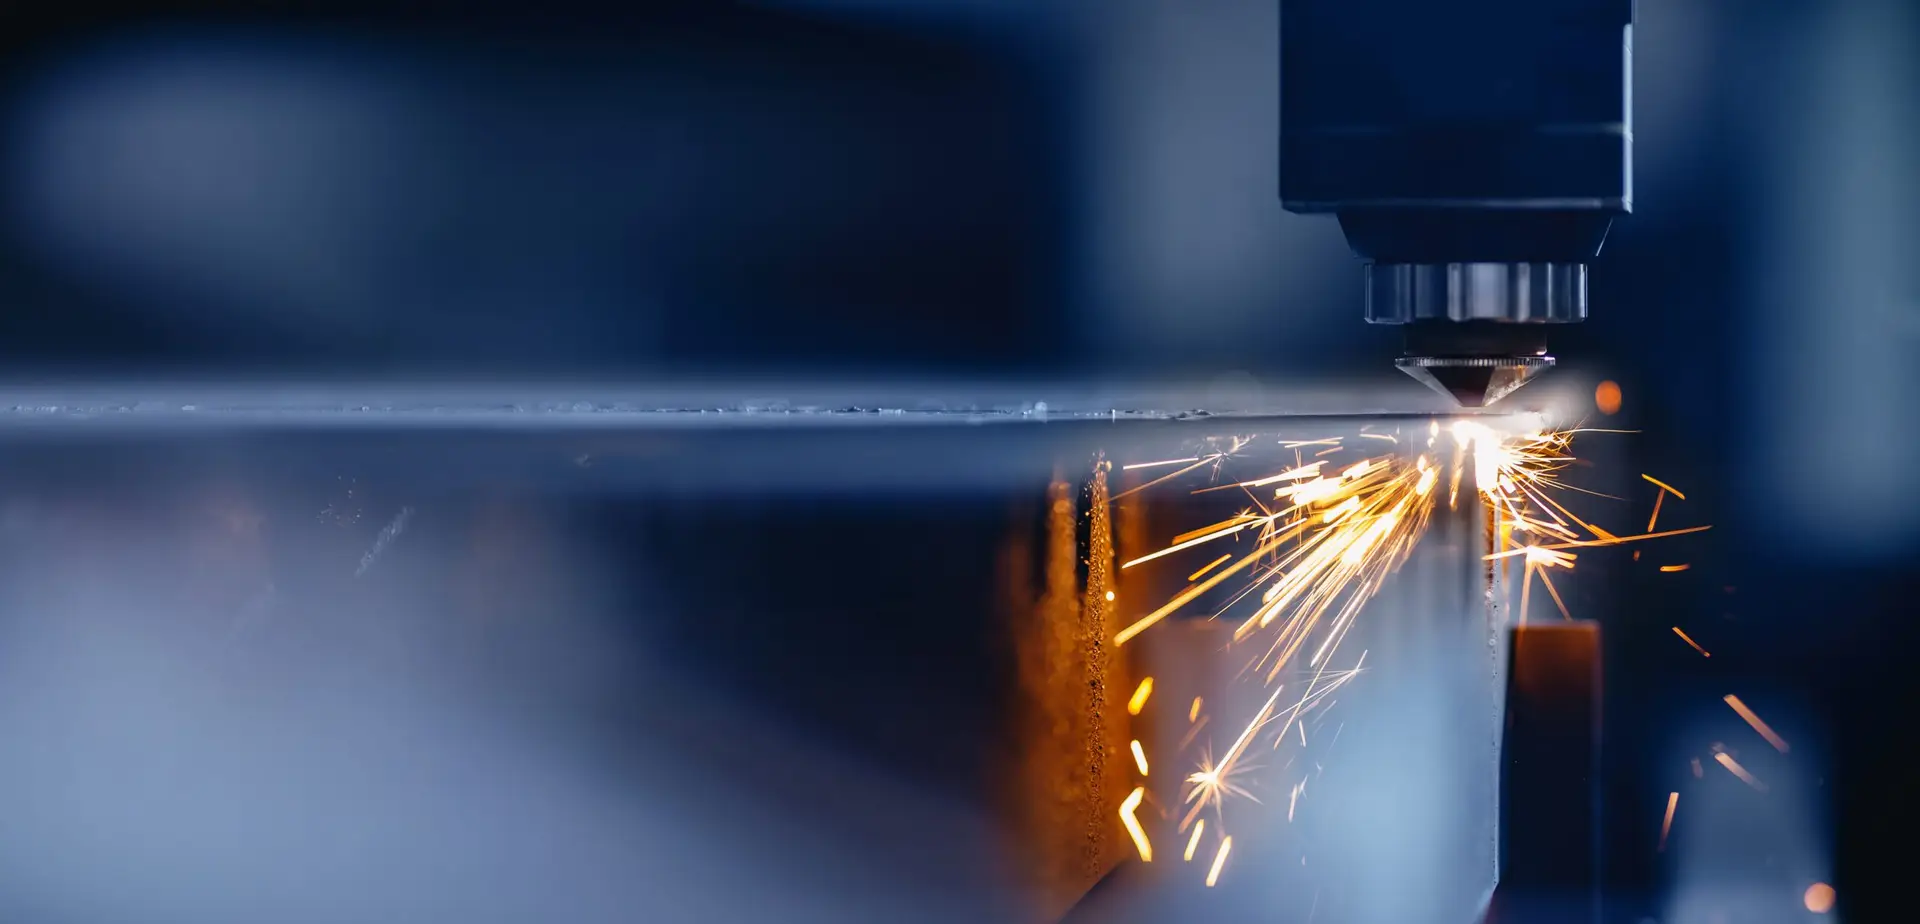
Open post Fiber laser cutting machines Texas: Dener USA sheet laser cutting carbon steel on 5x10 table with auto shuttle

CNC Fiber Laser Cutting Machines Are Reshaping Texas Fabrication in 2026

Southwest Machine Technologies | Houston, TX

Texas manufacturing entered 2026 with momentum. The Federal Reserve Bank of Dallas’s February 2026 Texas Manufacturing Outlook Survey reported solid production demand in the first half of the year, with machinery manufacturers describing their strongest order books in years — and fabrication shops among the most active buyers of new capital equipment in the state. That activity is not evenly distributed across technologies. One category is pulling significantly more investment than any other: fiber laser cutting machines.

The shift is structural, not cyclical. Texas fabricators serving energy infrastructure, structural steel, agricultural equipment, industrial machinery, and the Gulf Coast’s heavy manufacturing base are under simultaneous pressure to cut faster, waste less material, and hit tighter tolerances than plasma, oxy-fuel, or older CO2 systems can reliably deliver. Fiber laser technology resolves all three pressures at once — and 2026 is the year that has pushed that business case from compelling to urgent for shops still running conventional cutting lines.

What Is Driving Fiber Laser Investment Across Texas

The global laser cutting machine market is projected to nearly double over the next decade, growing from approximately $6.9 billion in 2025 to $14.3 billion by 2035. The U.S. market is forecast to grow at a 6.5 percent CAGR over the same period, driven by demand from aerospace, agricultural equipment, HVAC manufacturing, and contract metal fabrication — all sectors with significant concentration across Texas’s 254 counties. Within that broader market, fiber laser systems now account for the largest revenue share of any laser technology, reflecting a broad industry consensus that fiber is the performance and cost-efficiency standard for metal cutting.

The reasons are not difficult to understand. Fiber laser machines cut at speeds two to five times faster than CO2 systems on the same material thickness. They require no laser gas and have dramatically lower maintenance requirements because the beam is generated by solid-state optical components rather than a gas medium that degrades over time. Operating costs per part fall, uptime rises, and cut quality — measured by edge smoothness, kerf width, and heat-affected zone — consistently exceeds what older cutting technologies produce on steel, stainless, aluminum, brass, and copper.

For Texas fabricators running multiple shifts on high-volume part families, those differences compound into serious competitive advantages. A shop running a 10kW or 20kW fiber laser against a competitor still on a 4kW CO2 machine is not just cutting faster — it is winning jobs the competitor cannot quote profitably, holding tolerances the competitor cannot guarantee, and processing material thicknesses the competitor’s equipment cannot reach. The capital investment pays back through captured capacity, not just reduced operating cost.

The reshoring dynamic accelerating across Texas manufacturing amplifies this further. As explored in Tube Laser Cutting in Texas: Why Round, Square, and Rectangular Profiles Are the New Competitive Frontier, structural and industrial fabricators who have historically sourced cut tube components offshore are bringing that work back — and they need flat sheet and tube laser capability to handle it domestically.

Flat Sheet Fiber Lasers: Power, Table Size, and the Right Specification

For most Texas fabrication shops, the sheet laser decision involves three intersecting variables: table size, resonator power, and automation level. Each determines which part families the machine can handle profitably and at what volume.

Table configurations of 5’x10′, 6’x12′, and 8’x20′ cover the majority of sheet metal applications from light gauge HVAC components to heavy plate structural work. The 8’x20′ format in particular opens access to full-size plate processing for energy and industrial customers — a significant market in Texas — without requiring the material to be cut down before loading. Shops processing large format parts regularly can eliminate pre-cutting steps and their associated labor and handling costs entirely.

Resonator power selection follows the material matrix. At 3kW to 6kW, a fiber laser cuts thin to mid-gauge carbon steel, stainless, and aluminum at speeds that make short-run and prototype work economical. At 10kW to 20kW, the same machine processes material thicknesses that previously required plasma or oxy-fuel — but with laser-quality edges that require minimal or no secondary finishing. The 20kW range in particular is accelerating adoption in Texas’s heavy industrial sector, where thick carbon steel is the primary feedstock and edge quality directly affects downstream weld quality and assembly fit.

Auto shuttle table systems eliminate the downtime between part removal and sheet loading that limits productivity on manual-exchange machines. On a high-volume shop floor running twelve-hour shifts, shuttle automation can recover two or more production hours per day — the equivalent of running a second machine without the capital cost or floor space requirement. Combined with auto-focusing heads that optimize beam parameters in real time as material properties vary across a plate, these systems deliver the kind of consistent output that customer quality systems require.

Why 2026 Is the Inflection Point for Texas Shops

The Fabricators & Manufacturers Association’s 2026 outlook projects fabricated metals production growth of 5.5 percent in 2026 — more than double the 2.19 percent growth projected for 2025 and a sharp reversal of the slight contraction the sector saw in 2024. That growth, combined with the AI-driven boom in power infrastructure and data center construction (both heavy consumers of fabricated steel components), is creating the order volume that makes fiber laser investment justifiable for shops that have been watching the technology for two or three years without pulling the trigger.

The calculation has also become clearer on the cost side. High-power fiber laser systems from manufacturers with U.S.-based service and support infrastructure are now available at price points that mid-size Texas fabricators can finance with manageable payback periods — particularly when evaluated against the ongoing cost of subcontracting laser-cut components, the throughput limitations of their current cutting equipment, and the quality and delivery pressure from customers who have already come to expect laser-quality edges as table stakes.

For shops evaluating this investment, the service and support dimension is as important as the machine specification. A fiber laser system that maximizes uptime requires responsive local support when issues arise — not a shipping container to overseas parts inventory and an international support queue. That reality shapes how smart buyers approach the purchasing decision, which is examined more closely in How Texas Fabrication Shops Should Evaluate a Fiber Laser Purchase in 2026.

Southwest Machine Technologies

Southwest Machine Technologies serves fabrication shops throughout all 254 counties of Texas with high-performance CNC fiber laser cutting machines backed by dependable U.S. service and support.

Our Fiber Laser Offerings Include:

  • Dener USA Sheet Fiber Lasers — 5’x10′, 6’x12′, and 8’x20′ tables, 3kW–20kW resonators, auto shuttle table, auto-focusing head, FSCut control
  • Dener USA Tube Lasers — 20’–40′ tube processing lengths, 3kW–12kW, 2- and 3-chuck systems, auto loading/unloading, FSCut control

Ready to See What Fiber Laser Can Do for Your Shop? Contact SWMT to request a quote or discuss which system fits your material mix, volume, and budget.

Works Cited

“Texas Manufacturing Sector Growth Remains Solid.” Federal Reserve Bank of Dallas Texas Manufacturing Outlook Survey, Feb. 2026, www.dallasfed.org/research/surveys/tmos/2026/2602. Accessed 26 Mar. 2026.

“2026 Metal Fabrication Forecast: Growth Accelerates in a Divided Economy.” The Fabricator, Fabricators & Manufacturers Association, Dec. 2025, www.thefabricator.com/thefabricator/article/shopmanagement/2026-metal-fabrication-forecast-growth-accelerates-in-a-divided-economy. Accessed 26 Mar. 2026.

Related Articles


Open post Texas machinist shortage solutions: machine shop operator managing multiple multi-axis CNC machines simultaneously

The Machinist Shortage Is Reshaping Texas Machine Shops—Here’s How Shops Are Fighting Back

Southwest Machine Technologies: Precision Machining Solutions for Texas

The skilled machinist shortage has shifted from an inconvenience to an existential threat for Texas CNC shops. Across the state’s booming manufacturing corridor—from Gulf Coast energy fabricators to Dallas-Fort Worth aerospace subcontractors—shop owners report the same frustration: machines sitting idle not because orders are slow, but because there is nobody qualified to run them. The February 2026 Dallas Fed Manufacturing Survey captured this tension perfectly, showing wages and benefits pressures nearly doubling in a single month even as production expanded at above-average rates. Texas manufacturers are making more parts than they did a year ago, but the workforce math is getting harder, not easier.

The scope of the problem extends far beyond Texas. A joint study by Deloitte and The Manufacturing Institute found that U.S. manufacturers could need as many as 3.8 million new employees by 2033, with nearly half of those positions—1.9 million jobs—at risk of going unfilled if current workforce trends continue. CNC machinists and programmers represent a significant share of that gap. The shortage is not cyclical. It is structural, driven by a retirement wave that is pulling experienced operators out of the trade faster than apprenticeships, technical colleges, and on-the-job training programs can replace them.

For Texas specifically, the challenge is compounded by competition from other booming sectors. Construction, energy, and logistics all compete for the same pool of mechanically inclined workers who might otherwise consider machining careers. When warehouse operations near Houston or pipeline crews in the Permian Basin offer comparable starting wages with less perceived complexity, convincing a twenty-two-year-old to learn G-code and interpret blueprints becomes a tougher sell.

The Retirement Cliff Is Not Theoretical

The Bureau of Labor Statistics projects approximately 34,200 annual openings for machinists over the current decade, and virtually all of those openings stem from workers leaving the occupation through retirement or career changes rather than from net employment growth. The generation that built American precision machining—baby boomers who learned their craft on manual lathes before transitioning to CNC—is walking out the door, and taking decades of institutional knowledge with them.

Texas shops feel this acutely. A veteran machinist who can listen to a cut and diagnose chatter, who knows which insert geometry handles 4140 differently from 17-4 stainless, who can troubleshoot a program by reading the chips on the floor—that person cannot be replaced by a job posting. Their departure creates a capability gap that ripples through the entire operation, slowing setup times, increasing scrap rates, and forcing shop owners to turn away work they previously handled with confidence.

The downstream consequences are significant. When shops cannot staff machines, they either decline contracts or extend lead times, pushing customers toward alternative suppliers or offshore sourcing. In a state where reshoring and tariff-driven demand are creating historic opportunities for domestic manufacturers—a dynamic explored in detail in How Reshoring and Tariff Policy Are Driving CNC Equipment Investment Across Texas—the inability to capitalize on incoming work due to labor constraints represents a painful irony.

How Smart Shops Are Adapting

The most resilient Texas shops are not simply waiting for the labor market to correct itself. They are attacking the problem from multiple angles, and equipment strategy sits at the top of that list.

First, shops are investing in CNC machines with user-friendly controls that compress the learning curve for new operators. FANUC’s Manual Guide i conversational programming, available standard on many modern turning centers, allows operators to create programs directly at the machine using fill-in-the-blank menus rather than writing raw G-code from scratch. This capability means a mechanically capable worker with basic manufacturing aptitude can become productive on a CNC lathe in weeks rather than months. It does not eliminate the need for skilled programmers, but it dramatically expands who can run production parts during a shift.

Second, shops are increasing the machine-to-operator ratio by choosing equipment designed for reliability and unattended operation. Rigid box way lathes with electronic wire tension monitoring, automatic tool setters, and robust chip evacuation systems allow a single operator to oversee two or three machines simultaneously. When every operator effectively runs multiple spindles, a ten-person shop produces like a fifteen-person shop without adding headcount.

Third, Texas manufacturers are tapping into state workforce development resources. The Texas Workforce Commission’s Skills Development Fund provides grants to help employers partner with community and technical colleges for customized job training. The fund has been a cornerstone of the state’s workforce strategy since 1995, and manufacturers who pair equipment purchases with structured operator training programs can offset significant ramp-up costs while building a pipeline of capable machine operators.

The Equipment-Workforce Connection

The link between machine capability and workforce flexibility is one of the most underappreciated dynamics in modern manufacturing. A turning center that requires an experienced programmer to set up every job is a bottleneck in a labor-short environment. A turning center that an intermediate operator can set up using conversational programming, with rigid construction that forgives minor feed-rate miscalculations and delivers consistent surface finishes even when cutting parameters are not perfectly optimized, is a force multiplier.

This distinction matters most for the small and mid-size shops that form the backbone of Texas manufacturing. A sixty-person aerospace subcontractor in Fort Worth or a twenty-person oilfield machine shop in Odessa cannot maintain the dedicated programming departments that large OEMs staff. Their operators are their programmers, their setup techs, and often their quality inspectors. Equipment that consolidates these functions into an intuitive workflow does not just improve efficiency—it determines whether the shop can accept a new contract at all.

The broader picture of Texas manufacturing’s 2026 momentum—expanding production, rising orders, and intensifying wage pressures—is examined thoroughly in Texas Manufacturing Rebounds: Why CNC Turning Centers Are Central to the Lone Star State’s 2026 Growth Strategy. That context underscores a critical point: the shops positioning themselves to win are those treating equipment purchases and workforce development as a single integrated strategy, not two separate budget lines.

What Comes Next

The machinist shortage will not resolve itself through demographics alone. The pipeline of young workers entering the trade remains narrower than the outflow of retirees, and that math does not change quickly. Texas shops that thrive through this period will be those that lower the skill threshold required to operate their equipment productively, invest in structured training for every new hire, and leverage state programs designed to subsidize exactly this type of workforce development.

The opportunity on the other side is substantial. Shops that solve the labor equation while competitors struggle will capture market share, command better margins, and build reputations that attract both customers and job applicants. In a tight labor market, the best machinists gravitate toward shops running modern, well-maintained equipment—not toward facilities where they will fight aging machines and outdated controls every shift.

The recruitment advantage of modern equipment should not be underestimated. A job posting that lists current-generation FANUC controls, clean working environments, and structured training programs pulls candidates that a posting for manual lathe operators on thirty-year-old machines never will. Younger workers entering the trades expect digital interfaces, touchscreen controls, and technology that feels current rather than antiquated. The machine on your floor sends a message to every applicant who walks through the door about whether your shop is investing in its future—or clinging to its past.

Texas is home to over two dozen community colleges and technical schools with manufacturing and machining programs, from San Jacinto College in Houston to Texas State Technical College campuses in Waco, Harlingen, and beyond. Shops that build relationships with these institutions gain early access to graduating students and can shape curriculum to match the specific machines and controls on their floors. When a student trains on FANUC conversational programming in school and finds the same interface waiting at a local shop, the transition from classroom to production is measured in days rather than weeks.

Southwest Machine Technologies: Your Texas CNC Equipment Partner

Southwest Machine Technologies (SWMT) provides the highest quality machine tools, service, and support to manufacturers across all 254 Texas counties. Our sales team brings extensive shop floor experience, and our technicians provide installation, operator training, and ongoing machine maintenance on every product we sell.

Our Services Include:

  • SMART NL Series 2-Axis Turning Centers – Box way CNC lathes with FANUC 0i-TF Plus controls featuring Manual Guide i conversational programming, chuck sizes from 6″ to 24″, and the reliability Texas shops need
  • Complete Turning Solutions for Texas – 2-axis, 3-axis, multi-axis, and vertical turning centers from Smart Machine Tools, HNK, and Fuji Machine America

Ready to Solve Your Capacity Challenge? Contact SWMT to discuss how the right turning center can help your shop produce more with the workforce you have today.

Works Cited

“Manufacturers Need as Many as 3.8 Million New Employees by 2033.” The Manufacturing Institute, 2 Apr. 2024, themanufacturinginstitute.org/manufacturers-need-as-many-as-3-8-million-new-employees-by-2033/. Accessed 24 Feb. 2026.

“Skills Development Fund.” Texas Workforce Commission, State of Texas, www.twc.texas.gov/programs/skills-development-fund. Accessed 24 Feb. 2026.

Related Articles


Open post Texas manufacturing rebound 2026 puts CNC turning centers at the center of Lone Star growth.

Texas Manufacturing Rebounds: Why CNC Turning Centers Are Central to the Lone Star State’s 2026 Growth Strategy

Southwest Machine Technologies: Precision Machining Solutions for Texas

Texas factory floors are humming again. After a turbulent close to 2025 marked by soft orders and tariff uncertainty, the state’s manufacturing sector has snapped back with force in early 2026, posting above-average production expansion and the strongest capacity utilization numbers in months. For machine shops and contract manufacturers across the Lone Star State, this rebound is translating directly into new equipment decisions—and CNC turning centers sit at the center of that investment wave.

The Federal Reserve Bank of Dallas reported in its February 2026 Texas Manufacturing Outlook Survey that the production index held at 12.5, well above the long-run series average, while capacity utilization climbed to 11.8 and new orders remained firmly positive at 11.1. Perhaps most telling, the future production index surged to 34.3, signaling that Texas manufacturers expect a significant ramp-up in output by late summer. Wages and benefits pressures jumped to 31.9, nearly double January’s reading, confirming that the battle for skilled labor is intensifying even as production accelerates.

These numbers matter for anyone running a machine shop in Houston, Dallas-Fort Worth, San Antonio, or the Gulf Coast corridor. When orders rise and labor stays tight, shops must extract maximum productivity from every spindle hour available. That equation increasingly favors modern 2-axis CNC turning centers equipped with rigid box way construction, intuitive FANUC controls, and the torque to handle aggressive material removal rates across the steel, aluminum, and exotic alloys Texas manufacturers encounter daily.

A State Built for Manufacturing Momentum

Texas did not arrive at this moment by accident. The state’s manufacturing advantages are structural: no corporate income tax, the nation’s largest roadway and freight network, thirty-five foreign trade zones, and a workforce exceeding 15.5 million people—the youngest and fastest-growing labor pool in the country. Governor Abbott has repeatedly characterized “Made in Texas” as a global brand, and the data supports the claim. Texas has held the title of top exporting state for twenty-three consecutive years, and construction spending on manufacturing facilities has nearly tripled since 2020.

The current rebound is amplified by reshoring momentum. Over three trillion dollars in reshoring-related manufacturing investments have been announced across the United States since early 2025, driven by tariff pressures and federal incentives like permanent 100-percent bonus depreciation for new machinery. Texas, with its deep-water ports and energy infrastructure, is capturing a disproportionate share of that capital. Machine shops positioned to take on the resulting work—precision-turned components for energy, aerospace, defense, and automotive sectors—need equipment that can deliver tight tolerances, shift after shift, without the luxury of a fully staffed second crew.

The machinist shortage compounds the urgency. Understanding The Machinist Shortage Is Reshaping Texas Machine Shops—Here’s How Shops Are Fighting Back provides essential context for why equipment decisions matter more than ever. When experienced operators retire faster than new ones enter the trade, the machines themselves must compensate with ease of programming, rigidity under heavy cuts, and reliability that minimizes unplanned downtime.

Why Turning Centers Are Seeing Renewed Demand

Turning operations are foundational to virtually every manufacturing sector thriving in Texas right now. Oil and gas components, valve bodies, hydraulic fittings, aerospace bushings, automotive shafts, and medical device housings all begin on a lathe. The diversity of Texas industry—from Permian Basin energy equipment to Houston-area petrochemical hardware to defense subcontracting around Fort Worth—means shops need turning platforms versatile enough to handle short runs of complex alloys on Monday and long production runs of carbon steel on Thursday.

Modern 2-axis CNC lathes with box way construction meet this demand with a combination of vibration damping, thermal stability, and raw cutting force that slant-bed designs cannot always replicate in heavy-duty applications. Box ways excel in interrupted cuts and large-diameter work where rigidity determines both surface finish quality and tool life. For Texas shops machining tough materials like Inconel for downstream energy clients or 4140 steel for oilfield tools, that rigidity directly affects profitability.

FANUC 0i-TF Plus controls have become a common thread across many of these machines, and for good reason. The fifteen-inch touchscreen interface and Manual Guide i conversational programming lower the barrier for less experienced operators to become productive quickly—an increasingly critical factor when shops cannot find veteran machinists willing to work second shift. Conversational programming allows operators to create simple programs at the control without needing full G-code fluency, effectively expanding the pool of workers who can run the machine productively.

The U.S. Bureau of Labor Statistics projects roughly 34,200 annual openings for machinists over the coming decade, nearly all resulting from retirements and transfers rather than job growth. That replacement math means every Texas shop owner should be thinking about how their equipment choices either ease or worsen the hiring problem. Machines that are difficult to program, unreliable to maintain, or limited in capability shrink an already thin applicant pool.

The Equipment Investment Calculus in 2026

Several converging forces make 2026 a pivotal year for CNC turning center acquisitions across Texas. First, the One Big Beautiful Bill Act’s permanent bonus depreciation provision allows manufacturers to deduct the full cost of new machinery in the year of purchase through 2030. That tax treatment dramatically compresses payback periods and makes capital equipment purchases more attractive relative to leasing or continuing to run aging machines.

Second, reshoring is creating new work that did not exist in Texas shops twelve months ago. Components previously sourced from China, Mexico, or Southeast Asia are being pulled back into domestic supply chains, and turning work represents a significant share of that volume. Shops that invested in capacity before the wave hits will capture contracts that competitors with maxed-out spindle hours cannot.

The broader story of How Reshoring and Tariff Policy Are Driving CNC Equipment Investment Across Texas reveals the scale of this opportunity. From Section 301 duties on Chinese imports to the new Section 122 global surcharge proposals, trade policy is structurally favoring domestic production in ways that may persist for years regardless of which party controls Washington.

Third, the Texas Workforce Commission’s Skills Development Fund and similar state programs provide grants to help employers train workers on new equipment, offsetting some of the ramp-up costs associated with bringing a new turning center online. For shops investing in machines with user-friendly controls and conversational programming, these training dollars stretch further because operators reach competency faster.

The ripple effects extend to maintenance and uptime. Modern turning centers with proven servo systems, hardened and ground box ways, and robust spindle assemblies reduce the unplanned downtime that devastates production schedules when shops are already running thin on labor. When a machine goes down in a fully staffed shop, the operator moves to another station. When a machine goes down in a short-staffed shop, that capacity simply vanishes until the repair is complete. Reliability is not just a maintenance metric—it is a workforce multiplier.

The manufacturers who thrive through the rest of this decade will be those who treat equipment strategy as inseparable from workforce strategy. A capable, reliable, and easy-to-operate turning center does not simply make parts—it makes hiring easier, training faster, and margins wider in an environment where all three matter more than they have in a generation.

Southwest Machine Technologies: Your Texas CNC Equipment Partner

Southwest Machine Technologies (SWMT) provides the highest quality machine tools, service, and support to manufacturers across all 254 Texas counties. With over 125 years of combined team experience and a Houston-area facility, SWMT delivers installation, operator training, and machine maintenance on every product sold.

Our Services Include:

Ready to Upgrade Your Shop? Contact SWMT to discuss which turning center fits your production requirements and how our technicians can get you cutting chips fast.

Works Cited

“Texas Manufacturing Outlook Survey: February 2026.” Federal Reserve Bank of Dallas, 23 Feb. 2026, www.dallasfed.org/research/surveys/tmos/2026/2602. Accessed 24 Feb. 2026.

“Machinists and Tool and Die Makers: Occupational Outlook Handbook.” U.S. Bureau of Labor Statistics, U.S. Department of Labor, www.bls.gov/ooh/production/machinists-and-tool-and-die-makers.htm. Accessed 24 Feb. 2026.

Related Articles


Open post

How Reshoring and Tariff Policy Are Driving CNC Equipment Investment Across Texas

Southwest Machine Technologies: Precision Machining Solutions for Texas

American manufacturing is undergoing its most dramatic structural shift in decades, and Texas machine shops stand directly in the path of opportunity. Over three trillion dollars in reshoring-related investment commitments have been announced across the United States since early 2025, driven by a combination of aggressive tariff policy, federal tax incentives, and a bipartisan recognition that critical supply chains must move closer to home. For CNC equipment investment shops in Houston, San Antonio, Dallas-Fort Worth, and across the state, this wave is not abstract economic theory—it is showing up as purchase orders, quote requests, and the urgent need for additional spindle capacity.

The policy architecture fueling this moment is unprecedented in modern American manufacturing. The tariffs enacted in April 2025 established baseline duties of ten to fifteen percent on most imports and a punitive 125 percent rate on Chinese goods. Simultaneously, the One Big Beautiful Bill Act signed in July 2025 provided permanent 100-percent bonus depreciation for new machinery and full deductions for domestic manufacturing facility construction through 2030. The combination of sticks and carrots has created a clear economic incentive for companies to manufacture domestically rather than import, and machine shops are the primary beneficiaries of that calculus.

Texas is uniquely positioned to capture this reshoring volume. The National Institute of Standards and Technology’s Manufacturing Extension Partnership has documented how small and mid-size manufacturers—exactly the profile of most Texas machine shops—serve as the backbone of domestic supply chains. The MEP National Network has worked with tens of thousands of manufacturers across the country, supporting job creation and generating billions in cost savings through operational improvements. As reshoring accelerates, these shops are the ones tooling up to produce the precision-turned and milled components that previously arrived on container ships from Shenzhen or Guadalajara.

What Reshoring Actually Looks Like on a Shop Floor

The reshoring narrative often focuses on billion-dollar semiconductor fabs and electric vehicle gigafactories. Those investments matter, but the real volume impact for Texas machine shops comes from the thousands of smaller sourcing decisions happening across industrial supply chains every month. An oilfield equipment manufacturer in Houston who previously sourced valve bodies from a Chinese foundry is now quoting Texas machine shops. A defense contractor in Fort Worth pulling circuit board housings back from a Taiwanese supplier needs domestic CNC turning capacity. A medical device company shifting production from Juárez needs precision-machined components from a shop that can hold five-tenths on a three-inch bore.

These individual contracts are modest compared to factory announcements that make headlines, but they are the lifeblood of job shops and contract manufacturers. And they are accumulating. The February 2026 Dallas Fed Manufacturing Survey showed new orders holding firmly positive for the second consecutive month, with the future production index at 34.3—one of the strongest forward-looking readings in recent memory. Texas machinery manufacturers reported in the survey that “the floodgates have opened” and that they expect to be “firing on all cylinders” through 2026.

The challenge is that reshoring demand is arriving while the workforce is shrinking. The dynamic creates a powerful incentive to invest in CNC equipment that maximizes output per operator. Turning centers with rigid box way construction, automated features, and intuitive controls allow shops to accept reshored work without proportionally increasing headcount—a critical consideration when experienced machinists are in desperately short supply, as explored in detail in The Machinist Shortage Is Reshaping Texas Machine Shops—Here’s How Shops Are Fighting Back.

The Tariff Landscape and Its Equipment Implications

Tariff policy in 2026 remains volatile but directionally clear: imported manufactured goods face rising costs that favor domestic production. The Supreme Court’s February 2026 ruling striking down certain broad-based tariffs enacted under the International Emergency Economic Powers Act briefly created uncertainty, but the administration quickly pivoted to invoking Section 122 authority to impose a ten-percent global surcharge pending congressional approval. Regardless of the specific legal mechanism, the political consensus around trade protection appears durable.

For Texas machine shops, the implications are twofold. First, the work is coming. Components subject to tariffs become economically viable to produce domestically even at higher American labor rates, and shops with available capacity will capture that work. Second, raw material costs are rising. Steel, aluminum, and specialty alloys used in CNC turning and milling operations face their own tariff pressures, with some manufacturers reporting unpredictable input cost swings. Dallas Fed survey respondents noted that the raw materials price index remains well above its historical average, and one fabricated metal manufacturer reported closing a family business active since 1958 because customers either stopped buying or stopped paying on time.

This environment rewards shops that invest strategically in equipment capable of minimizing material waste, maximizing tool life, and maintaining tight tolerances that reduce scrap. Every rejected part in a high-material-cost environment hits harder than it did two years ago. Rigid, precise turning centers that deliver consistent first-pass quality are not luxuries—they are margin protection.

Texas Infrastructure Advantages Amplify the Opportunity

The Lone Star State’s structural advantages make it a natural magnet for reshoring-driven manufacturing investment. Texas maintains the nation’s largest roadway and freight network, thirty-five foreign trade zones, and over 240 million dollars in port investments. The state’s GDP exceeds 2.6 trillion dollars, which would rank eighth globally if Texas were a sovereign nation. No corporate income tax, predictable regulatory environment, and a workforce exceeding 15.5 million people round out an equation that consistently attracts manufacturing capital.

According to the National Association of Manufacturers, the manufacturing skills gap could leave 2.1 million jobs unfilled nationally by 2030, potentially costing the economy one trillion dollars annually. Texas is not immune to this challenge, but its younger-than-average workforce, extensive community college system, and state-funded training programs like the Skills Development Fund give it a relative advantage over states with older and less mobile labor pools.

The state’s energy sector provides an additional tailwind. Oil and gas operations require enormous quantities of precision-turned components—from downhole tools and completion equipment to surface valves and pump housings. When crude prices support drilling activity, machine shops across the Gulf Coast and Permian Basin see direct demand increases that compound the reshoring effect. Texas shops serving energy clients while simultaneously picking up reshored industrial work face a capacity squeeze that only new equipment can relieve.

The Investment Window Is Open

The convergence of reshoring demand, favorable tax treatment, and rising material costs creates a strategic window for Texas machine shops to invest in CNC turning and milling equipment. Permanent bonus depreciation means the full cost of a new turning center can be written off in the year of purchase, collapsing what would normally be a multi-year payback calculation into a single tax cycle. For profitable shops, this provision makes equipment acquisition more attractive than it has been in years.

The broader context of Texas manufacturing’s 2026 trajectory—above-average production expansion, strong new orders, and surging future expectations—is analyzed thoroughly in Texas Manufacturing Rebounds: Why CNC Turning Centers Are Central to the Lone Star State’s 2026 Growth Strategy. That momentum is not speculative; it is captured in survey data from eighty Texas manufacturing executives collected just weeks ago.

Shops that delay equipment investment risk missing the reshoring wave entirely. Lead times for new CNC machines, installation, and operator training mean that a decision made today translates to productive capacity three to six months from now. In a market where contracts are being awarded to shops that can demonstrate available capacity and reasonable lead times, waiting carries a real cost measured in lost revenue and lost customer relationships.

The manufacturers best positioned for what comes next are those pairing equipment investment with workforce strategy—acquiring machines that are reliable enough to run extended hours, intuitive enough for newer operators to learn quickly, and rigid enough to handle the heavy cutting that Texas manufacturing demands.

Southwest Machine Technologies: Your Texas CNC Equipment Partner

Southwest Machine Technologies (SWMT) provides the highest quality machine tools, service, and support to manufacturers across all 254 Texas counties. Based in the Houston metropolitan area, SWMT delivers installation, comprehensive operator training, and machine maintenance backed by over 125 years of combined team experience.

Our Services Include:

  • SMART NL Series 2-Axis Turning Centers – Box way CNC lathes with 6″ to 24″ chuck sizes, FANUC 0i-TF Plus controls, and the rigidity to handle aggressive cuts in tough Texas materials
  • Full Turning Machine Lineup – 2-axis, 3-axis, multi-axis, and vertical turning centers from Smart Machine Tools, HNK, and Fuji Machine America

Ready to Add Capacity? Contact SWMT to discuss which turning center matches your production needs and how our technicians can have you running parts quickly.

Works Cited

“Manufacturing Extension Partnership (MEP).” National Institute of Standards and Technology, U.S. Department of Commerce, www.nist.gov/mep. Accessed 24 Feb. 2026.

“2.1 Million Manufacturing Jobs Could Go Unfilled by 2030.” National Association of Manufacturers, 4 May 2021, nam.org/2-1-million-manufacturing-jobs-could-go-unfilled-by-2030-13743/. Accessed 24 Feb. 2026.

Related Articles


Open post

Texas Manufacturing Rebounds in 2026: Why Fiber Laser Technology Is Leading the Recovery

Southwest Machine Technologies: Precision Equipment for Texas Fabrication

Texas factory activity posted its strongest expansion signal in months during January 2026, marking a dramatic reversal from December’s contraction. The Federal Reserve Bank of Dallas reported the production index surged to 11.2 from negative 3.0—a swing of more than 14 points that signals renewed momentum across the state’s industrial base. For fabrication shops navigating this rebound, fiber laser technology cutting systems have emerged as the technology enabling manufacturers to capitalize on returning demand without the workforce expansion that remains stubbornly difficult.

The Dallas Fed’s Texas Manufacturing Outlook Survey captured this sentiment directly from business executives. New orders jumped 18 points to 11.8, while capacity utilization climbed 12 points to 7.1. One machinery manufacturer responding to the survey described conditions bluntly: “Business is booming. We are buying new equipment to increase production, since we are falling behind on our inventory requirements.”

This equipment investment surge reflects a broader transformation in how Texas manufacturers approach production capacity. Rather than competing for scarce skilled workers in a market where 79 percent of manufacturing executives cite labor shortages as their greatest challenge, shops are investing in automation technologies that multiply the output of existing teams. DENER fiber laser cutting machines for Texas sit at the center of this strategy.

The Technology Advantage Driving Investment

Fiber laser cutting machines deliver performance characteristics that make them particularly valuable during a manufacturing recovery. Unlike traditional CO2 laser systems, fiber technology converts electrical power to cutting energy at efficiencies between 20 and 30 percent—roughly three to four times better than CO2 alternatives. This efficiency translates directly to lower operating costs at precisely the moment when inflation and rising energy prices pressure margins.

The productivity gains extend beyond energy savings. Modern fiber laser systems routinely cut sheet metal three to five times faster than CO2 lasers, depending on material type and thickness. For a fabrication shop responding to the order surge the Dallas Fed documented, this speed advantage means the difference between capturing new business and turning away profitable work.

Processing capability further distinguishes fiber technology in the current market. Fabrication shops serving Texas industries from oil and gas to construction frequently work with reflective metals including aluminum, brass, and copper. Fiber lasers handle these materials that historically challenged CO2 systems, expanding the range of work shops can accept without specialized equipment changes. The U.S. Bureau of Labor Statistics manufacturing sector data shows fabricated metal product manufacturing remains among the largest manufacturing subsectors, with establishments increasingly requiring versatile cutting capability to serve diverse customer requirements.

Regional Dynamics Favoring Texas Fabricators

Texas manufacturers operate from an advantageous position as the national manufacturing landscape shifts. The state has claimed the Governor’s Cup award for job-creating relocation and expansion projects for thirteen consecutive years. The Texas Economic Development Corporation notes the state’s GDP now exceeds 2.6 trillion dollars—making it the eighth-largest economy globally if ranked as an independent nation.

This economic scale creates sustained demand for fabricated components across sectors from energy infrastructure to commercial construction. The Dallas Fed survey captured specific market opportunities: health care facility construction and data center projects are offsetting slowdowns in commercial office work, while new home construction projections point toward increased demand in the second half of 2026.

For fabrication shops positioned with modern fiber laser capability, understanding how to address the labor constraints that accompany growth becomes essential. Exploring How Texas Fabrication Shops Are Solving the Skilled Worker Shortage with Automation provides critical context for manufacturers balancing capacity expansion against workforce realities.

The investment patterns visible across Texas mirror broader industry trends. The global fiber laser market reached nearly 6.9 billion dollars in 2024 and projects growth at 11.1 percent annually through 2033. Manufacturing equipment suppliers report that automated laser cutting lines improve production throughput by 45 percent while reducing material waste by 18 percent through AI-powered nesting software.

What the Data Signals for Fabricators

The January manufacturing survey results require careful interpretation. While headline numbers signal expansion, business executives also expressed substantial uncertainty about conditions six months forward. Tariff policies, international trade dynamics, and the uneven recovery across manufacturing subsectors create planning challenges that sophisticated equipment investments can help address.

Fabricators who invested in fiber laser technology during previous cycles report advantages that compound during uncertain periods. The flexibility to process diverse materials means shops can pivot toward growing market segments—whether data center components, renewable energy infrastructure, or precision parts for the aerospace supply chain expanding across Texas.

Production economics favor modern fiber systems regardless of which specific sectors drive demand. Energy consumption that runs 30 to 40 percent below CO2 alternatives protects margins as utility costs fluctuate. Minimal maintenance requirements compared to gas-based laser systems reduce both direct costs and production interruptions that complicate delivery commitments.

Manufacturers evaluating fiber laser technology should understand the specific performance characteristics that differentiate available systems. Reading Fiber Laser vs. CO2: Which Cutting Technology Fits Your Texas Shop? provides technical comparison data essential for informed equipment decisions.

SWMT: Your Texas Partner for Fabrication Equipment

Southwest Machine Technologies provides fiber laser cutting systems from Dener USA engineered specifically for the demands Texas fabricators face. From sheet laser systems processing materials up to 20kW capacity to tube laser machines handling profiles up to 40 feet, SWMT delivers equipment matched to your production requirements.

Our Services Include:

  • Fiber Laser Systems – Sheet and tube laser cutting machines with power options from 3kW to 20kW
  • CNC Machine Tools – Complete milling and turning solutions for Texas manufacturing

Ready to Capitalize on the Texas Manufacturing Rebound? Contact SWMT to discuss how fiber laser technology can position your shop for growth.

Works Cited

“Growth Resumes in Texas Manufacturing.” Texas Manufacturing Outlook Survey, Federal Reserve Bank of Dallas, 26 Jan. 2026, www.dallasfed.org/research/surveys/tmos/2026/2601. Accessed 30 Jan. 2026.

“Manufacturing: NAICS 31-33.” Industries at a Glance, U.S. Bureau of Labor Statistics, www.bls.gov/iag/tgs/iag31-33.htm. Accessed 30 Jan. 2026.

Related Articles


Open post

How Texas Fabrication Shops Are Solving the Skilled Worker Shortage with Automation

Southwest Machine Technologies: Precision Equipment for Texas Fabrication

Texas fabrication shops face a workforce crisis that threatens their ability to capture growing demand. New research from CADDi’s 2026 Manufacturing Outlook Study reveals that 79 percent of manufacturing executives identify the skilled labor shortage as their greatest operational challenge—a figure that has persisted despite years of recruitment efforts, wage increases, and training programs. The manufacturing departments directly responsible for production are hit hardest, with 90 percent of companies reporting these areas experience the most severe staffing gaps.

The mathematics of this shortage are stark. Projections indicate 2.1 million manufacturing positions could remain unfilled by 2030, creating a constraint that no amount of job posting or salary adjustment can resolve. The talent pipeline simply cannot produce enough skilled workers to meet demand. For Texas fabricators watching new orders climb—the Dallas Fed’s January survey showed an 18-point surge in the new orders index—the question becomes how to capture this business without the workers traditionally needed to execute it.

The answer increasingly involves automation technologies that multiply the output of existing teams. Sixty-nine percent of manufacturers plan to invest in robots, equipment, and other physical assets in 2026—a nine percent increase from the previous year. This shift represents recognition that technology investment provides a more reliable path to capacity expansion than competing for workers who may not exist in sufficient numbers.

The Productivity Multiplier Effect

Fiber laser cutting systems exemplify how automation transforms fabrication shop economics. A single skilled operator overseeing modern fiber laser equipment produces output that previously required multiple workers on conventional machinery. The speed differential is dramatic: fiber lasers cut sheet metal three to five times faster than CO2 alternatives and orders of magnitude faster than mechanical cutting processes.

This speed translates to capacity without proportional headcount expansion. A fabrication shop adding a fiber laser system with automatic sheet loading can process significantly more material per shift with the same labor allocation. The technology handles material positioning, executes programmed cutting paths with micron-level precision, and presents completed parts for downstream operations—all with minimal operator intervention once jobs are programmed.

Understanding the broader context of Texas manufacturing’s current momentum helps fabricators evaluate technology investments strategically. Texas Manufacturing Rebounds in 2026: Why Fiber Laser Technology Is Leading the Recovery examines how state-level economic dynamics create opportunities for shops positioned with modern equipment capability.

Quality consistency compounds the productivity advantage. Human operators, regardless of skill level, experience fatigue and attention variation across shifts and weeks. Automated fiber laser systems maintain identical cutting parameters from the first part to the thousandth, eliminating the quality variation that generates scrap, rework, and customer complaints. For fabricators serving demanding industries from aerospace to energy infrastructure, this consistency often determines supplier qualification.

A Structural Shift in Workforce Strategy

Texas fabricators are responding to workforce constraints with focused capital deployment. The Manufacturing Institute reports that 77 percent of manufacturers anticipate ongoing difficulties attracting and retaining workers indefinitely—not as a temporary condition but as a permanent operating reality requiring structural response.

This structural shift favors equipment that reduces labor dependency while maintaining or improving output quality. Fiber laser technology aligns particularly well with these requirements. The systems process diverse materials including reflective metals that challenge other cutting methods, expanding the range of work shops can accept without specialized labor for each material type.

The automation investment surge extends beyond cutting operations. Manufacturers report increasing focus on integrated production systems where fiber lasers connect with automated material handling, inventory management, and quality verification. These integrated cells require fewer workers per unit of output while generating comprehensive production data that supports continuous improvement.

Operational Realities Driving Decisions

Fabrication shop owners making equipment decisions weigh multiple factors beyond labor scarcity. Energy costs represent an increasingly significant operating expense, and fiber laser technology delivers 30 to 40 percent energy savings compared to CO2 alternatives. This efficiency advantage compounds across production volume, generating savings that accumulate throughout equipment life.

Maintenance requirements further differentiate fiber systems in the current labor environment. Traditional CO2 lasers require regular mirror alignment, gas mixture management, and component servicing that demands specialized technical knowledge. Fiber lasers eliminate these maintenance categories entirely, reducing both direct service costs and the skilled technician time such maintenance consumes.

The CADDi research revealed that investment in operational systems like ERP and MES software fell sharply in 2026—dropping from 60 percent to 33 percent of companies prioritizing such spending. Manufacturers are redirecting capital toward technologies that deliver measurable output gains on the shop floor rather than administrative systems. Fiber laser equipment represents exactly the kind of productive asset that generates immediate, quantifiable return.

For shops evaluating specific equipment options, understanding the technical differences between cutting technologies provides essential decision support. Fiber Laser vs. CO2: Which Cutting Technology Fits Your Texas Shop? offers detailed comparison of performance characteristics, operating costs, and application suitability.

SWMT: Your Texas Partner for Fabrication Equipment

Southwest Machine Technologies delivers fiber laser systems engineered to maximize productivity while minimizing labor requirements. Dener USA’s sheet and tube laser platforms incorporate automatic shuttle tables, auto-focusing heads, and intuitive controls that enable rapid operator training and consistent production.

Our Services Include:

  • Fiber Laser Systems – Sheet processing from 5×10 to 8×20 tables with power options up to 20kW
  • Tube Laser Systems – Processing lengths up to 40 feet with automatic loading and unloading

Ready to Multiply Your Workforce Productivity? Contact SWMT to evaluate how fiber laser automation can address your capacity challenges.

Works Cited

“79% of Manufacturing Executives Say Skilled Labor Shortage is Greatest Challenge According to New CADDi Research.” Yahoo Finance, 20 Jan. 2026, finance.yahoo.com/news/79-manufacturing-executives-skilled-labor-150000740.html. Accessed 30 Jan. 2026.

“2.1 Million Manufacturing Jobs Could Go Unfilled by 2030.” The Manufacturing Institute, themanufacturinginstitute.org/2-1-million-manufacturing-jobs-could-go-unfilled-by-2030-11330/. Accessed 30 Jan. 2026.

Related Articles


Open post

Fiber Laser vs. CO2: Which Cutting Technology Fits Your Texas Shop?

Southwest Machine Technologies: Precision Equipment for Texas Fabrication

Texas fabrication shops evaluating laser cutting technology face a fundamental choice that shapes operating economics for years forward. Fiber laser and CO2 laser systems represent distinct approaches to metal cutting, each with performance characteristics that determine suitability for specific applications. Understanding these differences enables fabricators to match technology selection to their production requirements, material mix, and competitive positioning.

The global shift toward fiber technology reflects compelling performance advantages that have reshaped equipment markets. Industry analysis from Grand View Research shows fiber laser systems now account for 59 percent of new laser cutting installations, displacing CO2 technology that dominated the sector for decades. The global fiber laser market reached 6.87 billion dollars in 2024 and projects growth at 11.1 percent annually through 2033. This transition stems not from marketing but from measurable productivity and cost advantages that compound across production volume.

For Texas fabricators specifically, material processing requirements often favor fiber capability. Energy sector work frequently involves reflective metals including aluminum and copper that historically challenged CO2 systems. Construction and infrastructure projects demand throughput speeds that fiber technology delivers. For Texas fabricators ready to evaluate the switch, SWMT’s full line of DENER fiber laser cutting machines flat sheet and tube, 3kW to 20kW — is a useful starting point before working through the comparison below.

The Efficiency Differential

Energy consumption represents the most quantifiable difference between fiber and CO2 laser technology. According to technical documentation on laser cutting processes, fiber lasers convert electrical power to cutting energy at efficiencies between 20 and 30 percent. CO2 systems achieve only 5 to 10 percent efficiency, meaning they consume two to three times more electricity to perform equivalent cutting work.

This efficiency gap compounds across production hours. A fabrication shop running laser cutting equipment through extended shifts accumulates energy costs continuously. At Texas industrial electricity rates, the operating cost differential between fiber and CO2 systems can reach thousands of dollars monthly depending on utilization. Over typical equipment lifespans measured in years, these savings substantially offset initial investment premiums.

The efficiency advantage extends beyond direct utility costs. Higher electrical efficiency means less waste heat generation, reducing cooling system loads and facility HVAC requirements. Fiber laser resonators produce less heat than CO2 gas excitation systems, enabling more compact equipment footprints that maximize productive floor space utilization.

Speed and Throughput Capabilities

Cutting speed differentials between fiber and CO2 systems vary with material type and thickness but consistently favor fiber technology for typical fabrication materials. On thin to medium gauge steel, stainless steel, and aluminum—the materials constituting most fabrication work—fiber lasers cut three to five times faster than comparable CO2 systems.

This speed advantage translates directly to throughput capacity. A fabrication shop processing sheet metal with fiber laser equipment completes jobs in a fraction of the time CO2 systems require. For operations constrained by delivery commitments or backlog accumulation, speed determines competitiveness as directly as pricing.

The productivity implications extend beyond cutting cycles. Faster cutting means more parts per shift, spreading fixed overhead across larger production volume. Labor costs per part decrease because operator time distributes across more output. Texas Manufacturing Rebounds in 2026: Why Fiber Laser Technology Is Leading the Recovery details how these economics are driving equipment investment across the state’s expanding fabrication sector.

Material Processing Capabilities

Fiber laser technology excels at processing reflective metals that historically posed challenges for CO2 systems. Aluminum, brass, copper, and galvanized steel reflect CO2 laser wavelengths efficiently, reducing cutting effectiveness and potentially damaging beam delivery optics. Fiber laser wavelengths interact more favorably with these materials, enabling reliable processing without specialized precautions or reduced power settings.

For Texas fabricators serving diverse industries, this material flexibility expands addressable markets. Energy sector work includes copper busbars for electrical systems and aluminum components for various applications. HVAC and architectural fabrication involves galvanized steel and aluminum extensively. The ability to process these materials efficiently means capturing work that less capable equipment cannot handle reliably.

Thickness capabilities favor CO2 technology only at the extreme end of the range. For cutting very thick plate steel exceeding one inch, high-power CO2 systems maintain advantages in cut quality and edge characteristics. However, most fabrication work involves materials where fiber technology performs excellently, making CO2 advantages in thick material processing relevant only for specialized heavy plate applications.

Maintenance and Operating Considerations

Fiber laser systems require fundamentally less maintenance than CO2 alternatives, reducing both direct service costs and production interruptions. CO2 lasers depend on carefully aligned mirror systems, gas mixture management, and regular resonator servicing. These maintenance requirements demand skilled technicians and create scheduling constraints around service intervals.

Fiber lasers eliminate mirror alignment entirely—the laser beam travels through fiber optic cables rather than bouncing between mirrors. No cutting gas consumption occurs during the lasing process itself, removing gas supply logistics and cost. Resonator maintenance intervals extend substantially beyond CO2 equivalents, with many operations reporting years between major service requirements.

This reduced maintenance burden proves especially valuable given current workforce constraints. How Texas Fabrication Shops Are Solving the Skilled Worker Shortage with Automation explores how equipment choices that minimize specialized labor requirements help fabricators navigate the persistent talent shortage affecting the industry.

Consumable costs further differentiate the technologies. CO2 laser systems consume specialty gas mixtures continuously during operation, creating ongoing supply expenses and delivery logistics. Fiber systems require only assist gases for the cutting process itself—nitrogen, oxygen, or compressed air depending on material and quality requirements. These assist gases cost less and supply more readily than laser gas mixtures.

SWMT: Your Texas Partner for Fabrication Equipment

Southwest Machine Technologies supplies Dener USA fiber laser systems engineered for the performance demands Texas fabricators face. From compact 3kW systems for lighter duty work to 20kW configurations processing thick materials at production speeds, SWMT matches equipment capability to your operational requirements.

Our Services Include:

  • Fiber Laser Systems – Complete range of sheet and tube processing equipment with Texas-based support
  • Equipment Consultation – Technical guidance on system selection, facility requirements, and capability matching

Ready to Evaluate Fiber Laser Technology for Your Operation? Contact SWMT to discuss equipment options suited to your production requirements.

Works Cited

“Fiber Laser Market Size and Share.” Grand View Research, www.grandviewresearch.com/industry-analysis/fiber-laser-market-report. Accessed 30 Jan. 2026.

“Laser Cutting.” Wikipedia, Wikimedia Foundation, en.wikipedia.org/wiki/Laser_cutting. Accessed 30 Jan. 2026.

Related Articles


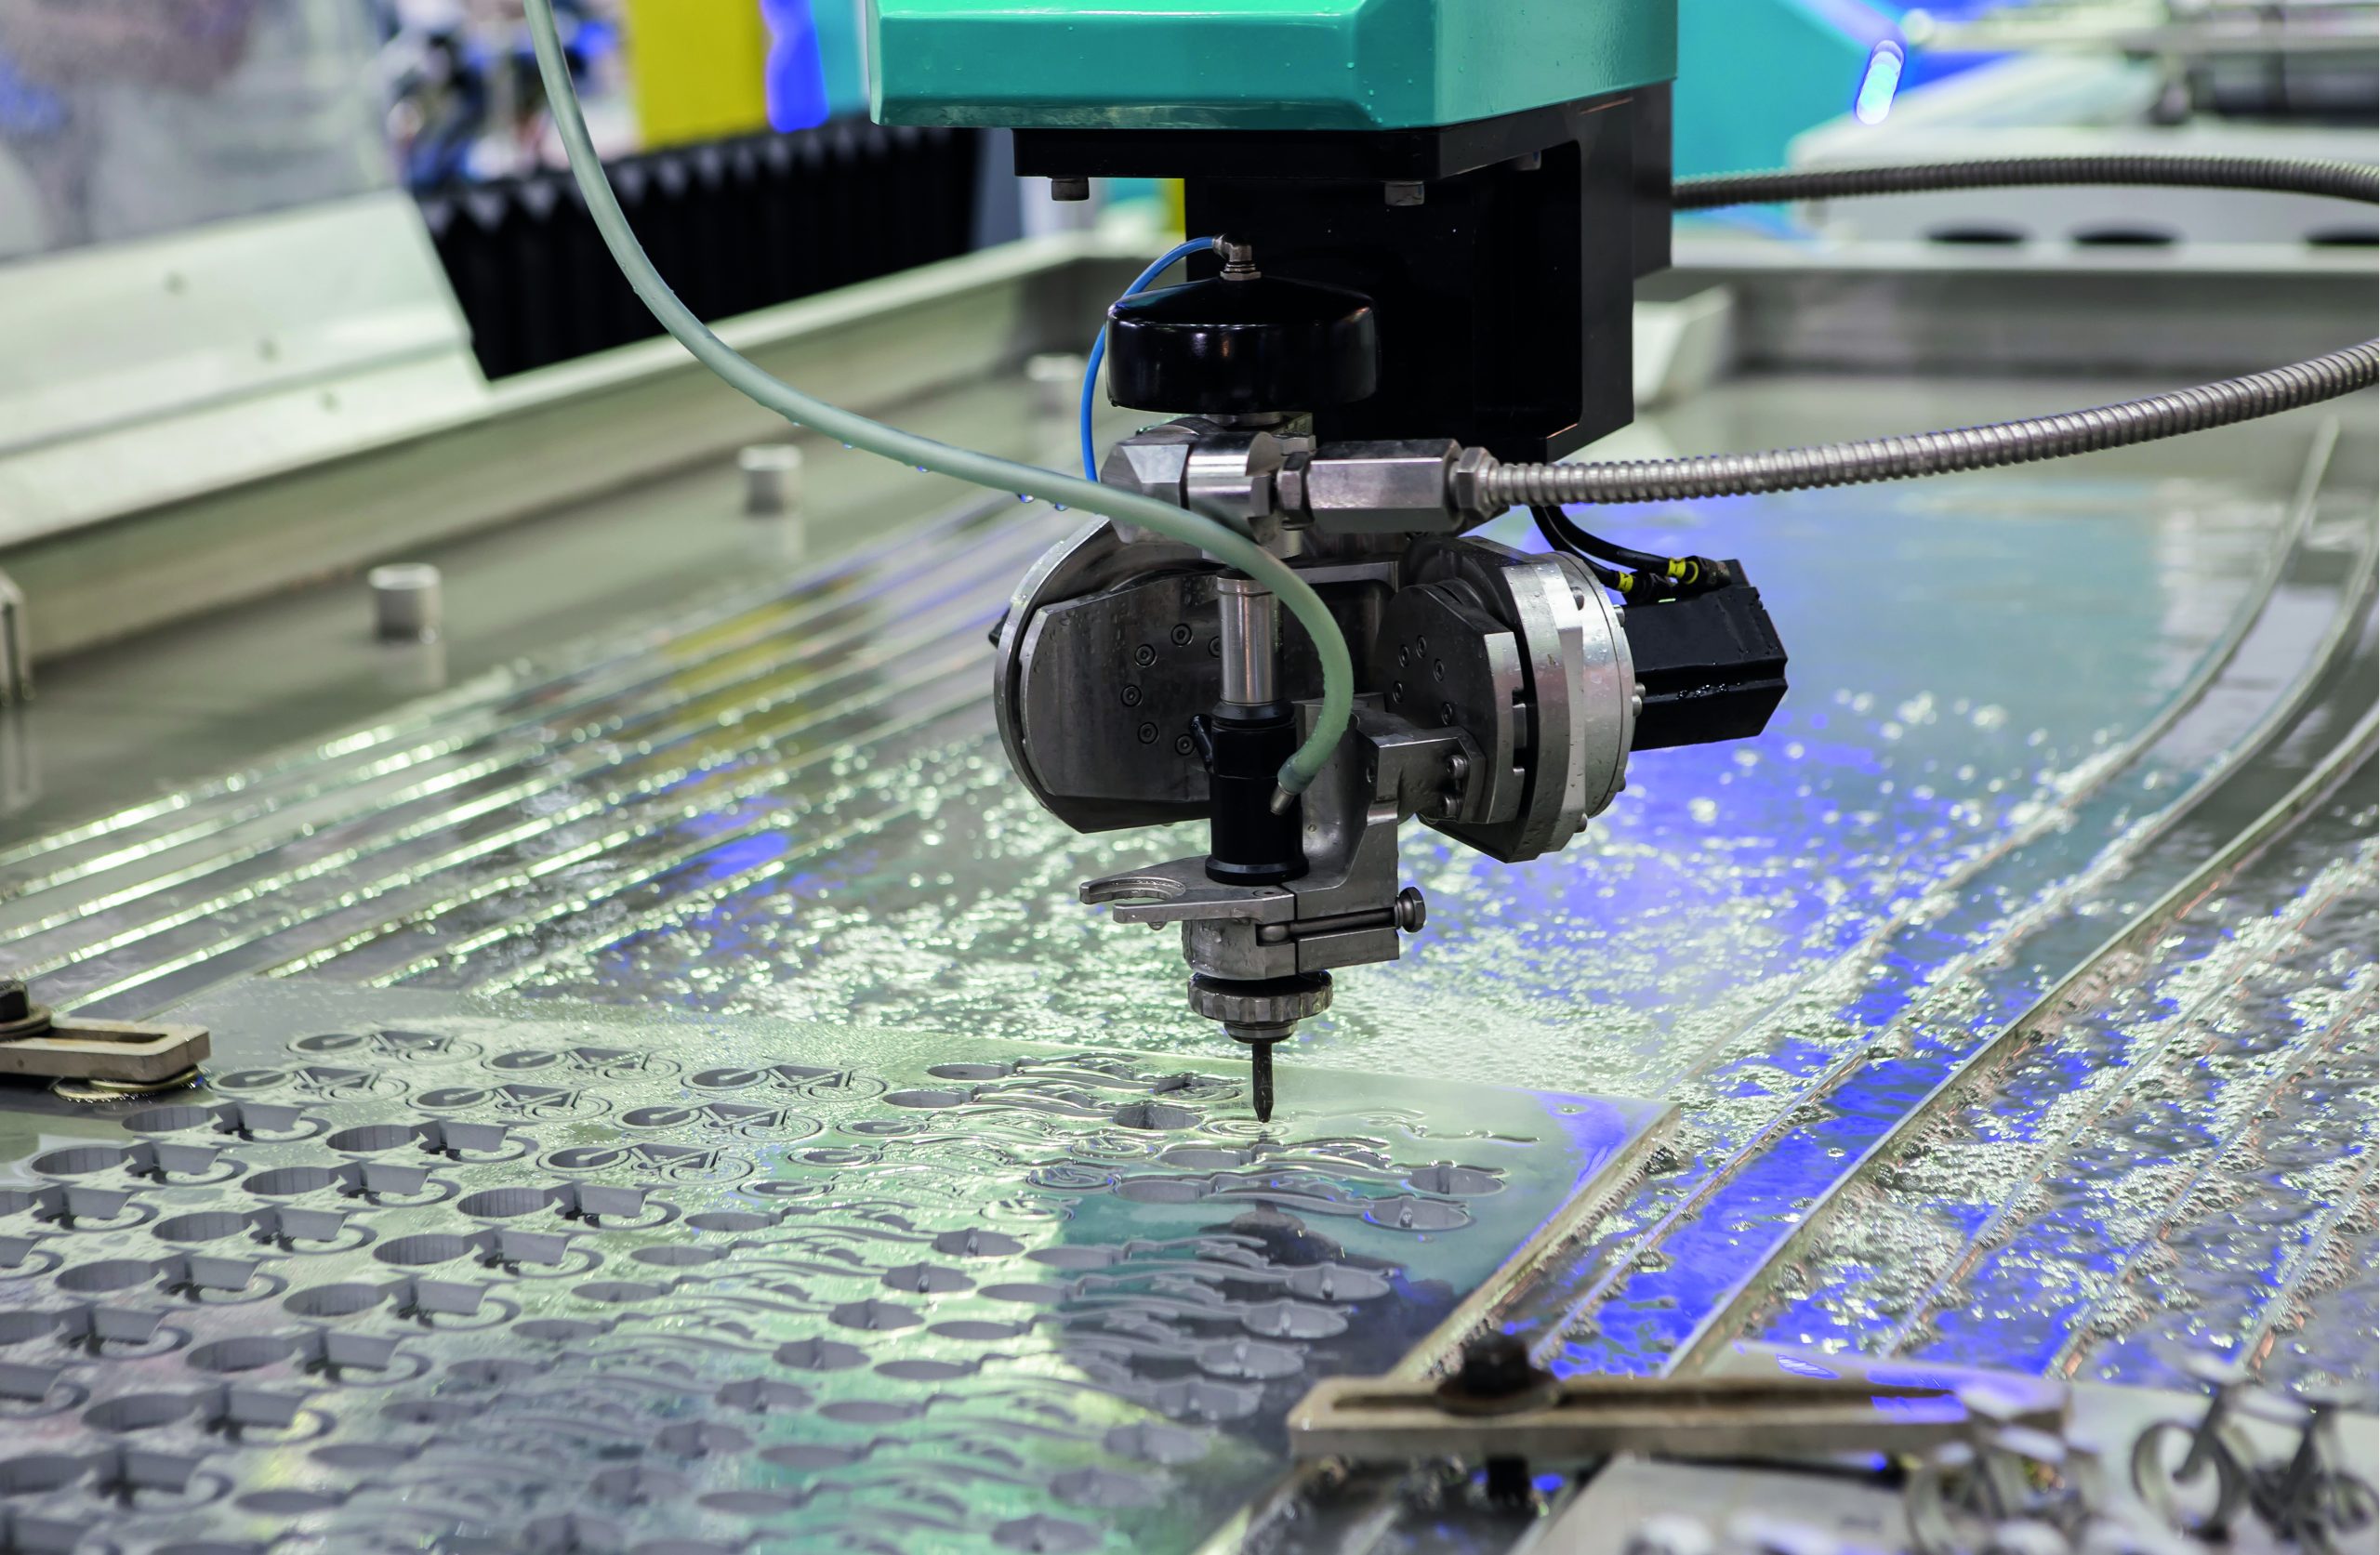
Open post A high-pressure waterjet cutting technology, cutting a complex titanium aerospace component in a Texas.

Waterjet Cutting Technology Gains Ground in Texas Metal Fabrication Operations

Southwest Machine Technologies: Providing High Quality Products at Unmatched Value with Unrivaled Support

The global waterjet cutting machine market reached $1.41 billion in 2025 and is projected to expand to $2.20 billion by 2032, growing at 6.6 percent annually according to recent industry analysis. North America commands over 40 percent of worldwide market share, with the United States waterjet equipment sector specifically projected to grow from $305 million in 2024 to nearly $400 million by 2033. Texas ranks among the leading industrial states driving this expansion, with the state’s diversified manufacturing base in oil and gas equipment, metal fabrication, aerospace, and construction creating sustained demand for precision cutting technology that preserves material integrity.

Waterjet cutting technology has emerged as a critical capability for manufacturers requiring precision processing across diverse materials without the thermal distortion associated with plasma, laser, or flame cutting methods. The technology accelerates water to supersonic speeds—often mixed with abrasive garnet particles—to cut through metals, composites, stone, glass, and virtually any material with tolerances measured in thousandths of an inch. For Texas fabricators serving aerospace contractors, energy equipment manufacturers, and precision component customers, waterjet systems deliver cutting versatility that single-technology shops cannot match.

The technology adoption aligns with broader equipment modernization trends reshaping Texas manufacturing. As detailed in Texas Manufacturers Face Equipment Modernization Pressure as Production Activity Accelerates, production output surged while employment remained flat—evidence that capacity expansion increasingly depends on equipment capability rather than workforce growth. Waterjet systems contribute to this productivity equation by enabling shops to process work previously requiring outsourcing or multiple cutting technologies, consolidating capabilities that improve throughput and reduce lead times.

Cold Cutting Advantages Drive Adoption

The fundamental distinction separating waterjet cutting from thermal processes lies in heat-affected zones—or rather, their absence. Plasma, laser, and flame cutting generate temperatures exceeding several thousand degrees, creating metallurgical changes in material adjacent to cut edges. These heat-affected zones can alter hardness, introduce brittleness, cause warping, and compromise material properties that engineers specified for performance reasons. Aerospace components, medical devices, and precision mechanisms cannot tolerate these thermal effects without risking performance degradation or premature failure.

Waterjet cutting eliminates thermal distortion entirely because the process generates no significant heat at the cutting interface. The Fortune Business Insights waterjet market analysis identifies cold cutting capability as a primary driver of technology adoption, noting that manufacturers increasingly demand precision processes preserving material integrity without thermal effects. This characteristic makes waterjet essential for cutting heat-sensitive materials including titanium alloys, tool steels, and advanced composites where post-cutting heat treatment or stress relief would otherwise be required.

Material versatility extends waterjet applications beyond traditional metal fabrication into diverse industrial sectors. A single waterjet system can cut aluminum for aerospace applications, stainless steel for food processing equipment, glass for architectural installations, and rubber for gasket production—all without tool changes or equipment reconfiguration. This flexibility proves particularly valuable for job shops and contract manufacturers serving varied customer requirements, enabling them to accept work across multiple industries rather than specializing narrowly in materials compatible with single cutting technologies.

Edge quality from waterjet cutting frequently eliminates secondary finishing operations required after thermal processes. Cut edges emerge smooth and burr-free, often ready for welding, assembly, or final use without grinding, deburring, or machining. This process efficiency reduces total manufacturing time and cost while improving consistency across production quantities. For Texas manufacturers competing on delivery speed and price, the elimination of secondary operations translates directly into competitive advantage.

Texas Industrial Base Drives Regional Demand

Texas manufacturing diversity creates waterjet demand across multiple industrial sectors simultaneously. The state’s energy industry requires precision-cut components for drilling equipment, pipeline fittings, valve bodies, and processing machinery. Aerospace contractors throughout the Dallas-Fort Worth and Houston regions need complex titanium and aluminum parts for aircraft structures and engines. Construction equipment manufacturers demand heavy steel fabrication with the precision that waterjet technology delivers for critical load-bearing components.

The Coherent Market Insights waterjet analysis documents that automotive applications dominate overall waterjet equipment demand in 2025, with aerospace, metal fabrication, and construction representing additional major market segments. Texas manufacturers serve all these sectors, creating concentrated regional demand for waterjet capabilities that support production across diverse customer requirements. Shops investing in waterjet technology position themselves to pursue opportunities across multiple industries rather than depending on single-sector demand cycles.

The 3D waterjet cutting segment commands 42 percent of market share, reflecting growing demand for complex geometry processing that two-dimensional cutting cannot address. Five-axis waterjet systems manipulate cutting heads through multiple angles simultaneously, producing beveled edges, compound cuts, and three-dimensional shapes from flat stock. Texas manufacturers serving aerospace and energy customers increasingly require these capabilities for components with complex geometries that would otherwise demand expensive five-axis machining operations.

Texas’s pro-business environment and infrastructure advantages amplify equipment investment returns. Manufacturers benefit from lower operating costs, favorable tax treatment, and logistics connectivity that enhance competitiveness against rivals in higher-cost regions. Equipment investments that improve capability and efficiency compound these structural advantages, enabling Texas shops to win work from customers throughout North America who might otherwise source locally or offshore.

Technology Integration and Automation Trends

Modern waterjet systems integrate extensively with CNC controls, CAD/CAM software, and production management systems that optimize cutting efficiency while reducing operator intensity. Nesting software automatically arranges parts on material sheets to minimize waste, often achieving material utilization exceeding 90 percent on complex part mixes. Cutting path optimization reduces head travel time between cuts while managing pierce sequencing to prevent part movement during processing. These software capabilities transform waterjet from a standalone cutting tool into an integrated manufacturing system generating data for production planning and quality documentation.

Hardware innovations continue expanding waterjet capabilities and economics. Ultra-high-pressure pumps exceeding 90,000 PSI enable faster cutting speeds and improved edge quality compared to earlier generation equipment operating at lower pressures. Abrasive delivery systems precisely meter garnet consumption, reducing operating costs while maintaining cut quality. Automatic head height sensing compensates for material variations, maintaining optimal standoff distance without operator intervention. Each advancement improves the cost-per-part economics that determine waterjet competitiveness against alternative cutting technologies.

The relationship between waterjet and CNC machining technologies deserves attention from manufacturers evaluating equipment investments. As examined in CNC Machine Market Surges Past $100 Billion as Texas Shops Invest in Precision Equipment, precision machining demand continues accelerating across Texas manufacturing. Waterjet cutting frequently serves as an upstream process producing near-net-shape blanks that CNC machines finish to final specifications. Shops operating both technologies capture more value from customer work while controlling quality throughout the manufacturing sequence.

Maintenance and consumable economics factor significantly into waterjet ownership calculations. Cutting heads, orifices, mixing tubes, and high-pressure seals require periodic replacement based on operating hours and cutting conditions. Abrasive garnet represents the largest ongoing consumable expense, with consumption rates varying based on material thickness, cutting speed, and quality requirements. Manufacturers evaluating waterjet investments should model total operating costs including consumables, maintenance, and utilities alongside capital equipment expenses to understand true cost-per-part economics.

Application Diversity Across Texas Industries

Aerospace manufacturing represents a particularly strong waterjet application in Texas given the state’s concentration of aircraft production, maintenance, repair, and overhaul facilities. Titanium, Inconel, and aluminum alloys used extensively in aerospace applications cut cleanly with waterjet while resisting efficient processing through many alternative methods. The absence of heat-affected zones satisfies aerospace quality requirements that often prohibit thermal cutting methods for flight-critical components. Aerospace contractors increasingly specify waterjet cutting in manufacturing planning, creating demand that equipped shops can capture while competitors lacking capability cannot pursue.

Energy sector applications span equipment manufacturing, maintenance, and field fabrication throughout Texas oil and gas operations. Valve bodies, flange blanks, and pressure vessel components require precision cutting from materials including carbon steel, stainless steel, and specialty alloys. Waterjet capability enables shops to process these diverse materials without maintaining multiple cutting technologies, simplifying operations while expanding addressable markets. Field service applications benefit from portable waterjet systems capable of on-site cutting for maintenance and repair work where shop fabrication proves impractical.

Architectural and artistic applications represent growing waterjet markets as designers specify intricate patterns in stone, metal, and glass that only waterjet can economically produce. Texas construction growth generates demand for custom architectural elements including lobby features, facade panels, and decorative metalwork. Shops positioned to serve architectural markets diversify revenue beyond industrial manufacturing while commanding premium pricing for design-intensive work requiring programming expertise alongside cutting capability.

Food processing equipment manufacturing benefits from waterjet’s ability to cut stainless steel cleanly without contamination concerns associated with some cutting processes. Texas food processing operations require equipment fabrication meeting sanitary standards that waterjet cutting supports through clean edges and absence of thermal effects that might compromise corrosion resistance. This application illustrates how waterjet capabilities open market opportunities that shops limited to thermal cutting methods cannot address.

Investment Considerations for Texas Fabricators

Equipment selection involves tradeoffs between capability, cost, and operational requirements that each manufacturer must evaluate based on their specific circumstances. Entry-level waterjet systems provide basic cutting capability at lower capital costs but may limit cutting speed, material thickness capacity, or precision compared to higher-specification equipment. Production-focused systems designed for industrial throughput command premium prices but deliver economics that justify investment for shops with sufficient volume to utilize capacity.

Table size determines maximum part dimensions and influences material handling efficiency for production operations. Larger tables accommodate bigger workpieces while enabling efficient nesting of multiple smaller parts that maximize material utilization. However, larger tables require more floor space, higher pump capacity, and greater capital investment. Manufacturers should evaluate typical part sizes and production volumes when specifying table dimensions rather than defaulting to maximum available sizes.

Pump pressure and horsepower directly affect cutting speed and edge quality, with higher specifications enabling faster processing of thick materials while potentially improving surface finish. Ultra-high-pressure systems cutting at 90,000 PSI or above achieve speeds approximately 50 percent faster than standard 60,000 PSI equipment on equivalent materials, improving throughput economics for production applications. The pressure decision involves balancing capital cost premiums against operating efficiency gains based on anticipated production requirements.

Southwest Machine Technologies: Your Texas Waterjet Equipment Partner

Southwest Machine Technologies serves manufacturers across all 254 Texas counties with industry-leading fabrication equipment and comprehensive service support. Our CMS waterjet systems—including the Tecnocut Smartline, Proline, and Aquatec platforms—deliver precision cutting capabilities engineered for demanding production environments.

Our Fabrication Equipment Solutions Include:

  • Fabrication Machines – CMS waterjet cutting systems and Cosen saws providing versatile material processing for Texas manufacturers
  • Complete Equipment Integration – Waterjet systems complementing milling, turning, and sawing equipment for comprehensive fabrication capabilities

Ready to Expand Your Cutting Capabilities? Contact Southwest Machine Technologies to discuss how waterjet technology can diversify your fabrication capabilities and position your operation for growth across Texas manufacturing’s expanding markets.

Works Cited

“Waterjet Cutting Machine Market Analysis & Forecast: 2025-2032.” Coherent Market Insights, 29 Jul. 2025, www.coherentmarketinsights.com/market-insight/waterjet-cutting-machine-market-3290. Accessed 9 Dec. 2025.

“Waterjet Cutting Machines Market Size, Share & Industry Analysis.” Fortune Business Insights, 24 Nov. 2025, www.fortunebusinessinsights.com/waterjet-cutting-machines-market-102026. Accessed 9 Dec. 2025.

Related Articles


Open post

Texas Manufacturers Face Equipment Modernization Pressure as Production Activity Accelerates

Southwest Machine Technologies: Providing High Quality Products at Unmatched Value with Unrivaled Support

Texas factory activity expanded at a markedly faster pace in November 2025, with the production index jumping 15 points to 20.5 according to the Federal Reserve Bank of Dallas—a reading indicating the strongest output growth the state has seen in months. Capacity utilization surged 21 points to 19.4, and shipments climbed nine points to 15.1, signaling that manufacturers across the Lone Star State are running harder than they have all year. Yet this acceleration arrives alongside persistent challenges that threaten to constrain growth: workforce shortages exceeding 60,000 positions in manufacturing alone, rising raw material costs, and equipment modernization demands that many shops struggle to meet.

The pressure on Texas manufacturers reflects a broader reality reshaping American industrial production. Companies that invested in modern fabrication equipment before the current expansion find themselves positioned to capture demand. Those still running aging machinery face capacity constraints precisely when orders are flowing. The Dallas Fed Texas Manufacturing Outlook Survey documented this tension directly, with raw materials prices jumping to 35.3 on their index—the highest sustained pricing pressure in over two years—while finished goods prices rose to 10.8 as manufacturers passed costs downstream.

The equipment decisions Texas manufacturers make today will determine their competitive position for the next decade. Waterjet cutting systems, CNC machining centers, and precision fabrication equipment represent capital investments that enable shops to accept work they would otherwise decline. For metal fabricators serving aerospace, automotive, energy, and construction sectors across Houston, Dallas, San Antonio, and Austin, equipment modernization has shifted from optional upgrade to operational necessity.

Production Growth Meets Capacity Constraints

The November production surge caught many Texas manufacturers operating near their limits. Seventeen percent of firms reported net hiring while sixteen percent reported layoffs—essentially flat employment despite accelerating output. This paradox reveals the real constraint facing the sector: not demand, but capacity and capability to fulfill it. Manufacturers are pushing existing equipment and existing teams harder rather than expanding, a strategy that generates short-term results but creates long-term vulnerabilities in quality, maintenance, and employee retention.

Hours worked increased 15 points to 9.9, confirming that Texas manufacturers achieved their output gains through overtime rather than workforce expansion. The approach makes economic sense when orders are uncertain, but November’s data suggested anything but uncertainty in demand. New orders climbed to 4.8 from negative territory, and future production expectations jumped to 33.7—the strongest forward-looking indicator in months. Manufacturers expect activity to remain elevated, creating pressure to translate temporary capacity stretches into permanent capability expansions.

The equipment intensity of modern manufacturing means capital investment often delivers greater returns than headcount expansion. A single waterjet cutting system or multi-axis machining center can accomplish work that previously required multiple operators on conventional equipment. Automation doesn’t eliminate jobs so much as redefine them, transforming machine operators into equipment technicians capable of programming, maintaining, and optimizing sophisticated production systems. This evolution explains why manufacturers facing worker shortages increasingly turn to equipment modernization as their primary growth strategy.

Understanding how precision equipment investments are reshaping fabrication capabilities across the state, as explored in CNC Machine Market Surges Past $100 Billion as Texas Shops Invest in Precision Equipment, provides context for the capital decisions manufacturers face. The choice between incremental upgrades and transformational equipment investments often determines whether shops capture growth or lose ground to better-equipped competitors.

Workforce Challenges Amplify Equipment Imperatives

Texas manufacturing confronts a workforce gap that traditional hiring alone cannot close. The National Association of Manufacturers reports the sector faces a consistent shortage exceeding 60,000 workers statewide, with positions in technical roles like machinists, welders, and equipment technicians proving especially difficult to fill. The Texas Workforce Commission notes that only 32 percent of Texas workers currently possess qualifications matching available jobs, while 47 percent of positions require postsecondary skills training that the educational pipeline delivers too slowly.

The workforce mathematics force manufacturers toward equipment solutions. When skilled operators prove scarce, equipment that reduces operator intensity per part produced becomes strategically valuable. Modern fabrication machines incorporate features specifically designed to address skill shortages: conversational programming interfaces that reduce training time, automated tool changers that minimize setup complexity, and real-time monitoring systems that catch errors before they generate scrap. Equipment investments become workforce investments when they enable existing employees to accomplish more.

The Fortune Business Insights CNC machine market analysis projects the global market growing from $101.22 billion in 2025 to $195.59 billion by 2032, driven substantially by manufacturers seeking automation solutions for labor constraints. The U.S. market specifically is expected to reach $15.03 billion by 2032, with aerospace, automotive, and precision engineering sectors leading adoption. Texas manufacturers participate in this global equipment trend while facing regional competitive dynamics that make modernization particularly urgent.

The equipment-workforce relationship extends beyond productivity metrics to encompass talent attraction. Manufacturers operating modern equipment find recruiting easier than those running decades-old machinery. Technical workers with CNC programming skills and automation experience gravitate toward shops where their capabilities translate into interesting work rather than frustrated workarounds for obsolete systems. Equipment modernization thus compounds its benefits—enabling higher productivity while simultaneously improving the talent pool available to achieve it.

Regional Manufacturing Strength Creates Opportunity

Governor Abbott’s proclamation of Manufacturing Week 2025 highlighted Texas as the manufacturing capital of the nation, home to a sector driving the state’s $2.7 trillion economy—the eighth largest in the world. The recognition reflects reality: Texas manufacturers benefit from geographic advantages, energy access, regulatory environment, and market proximity that competitors in other states cannot replicate. These structural advantages translate into growth opportunities for manufacturers positioned to capture them.

The Dallas-Fort Worth area requires an estimated 130,000 additional skilled workers over the next decade to maintain current growth trajectories, according to Federal Reserve Bank of Dallas research. Houston’s manufacturing base continues expanding around energy, aerospace, and industrial equipment sectors. San Antonio and Austin add manufacturing employment as technology companies localize production. Each metropolitan area’s growth creates demand for fabrication services that equipped manufacturers can fulfill—and that under-equipped operations must decline.

State workforce development initiatives recognize the equipment dimension of manufacturing competitiveness. Programs like Texas A&M Engineering Extension Service’s advanced manufacturing training facilities in Brownsville and the Coastal Bend prepare workers for careers operating sophisticated production equipment. The state’s emphasis on Industry 4.0 readiness acknowledges that modern manufacturing increasingly depends on digital integration, automation, and precision capabilities that only advanced equipment provides.

The regional dynamics of waterjet cutting technology, examined in Waterjet Cutting Technology Gains Ground in Texas Metal Fabrication Operations, illustrate how specific equipment categories are reshaping competitive landscapes across Texas manufacturing sectors. Fabricators adding waterjet capabilities access work streams previously unavailable, from aerospace composites to architectural metals to precision industrial components.

Price Pressures and Investment Decisions

Raw material costs represented the most significant pressure point in November’s manufacturing survey, with the index reaching 35.3—well above historical averages and indicating sustained input price increases. Manufacturers reported finished goods price increases reaching 10.8, but the gap between input and output pricing suggests margin compression that many operations cannot sustain indefinitely. Equipment that reduces material waste, improves first-pass yields, and accelerates production cycles directly addresses this margin pressure.

The investment calculus for fabrication equipment increasingly incorporates not just production speed but material efficiency. Waterjet cutting systems generate minimal kerf waste compared to traditional cutting methods. Multi-axis machining centers produce complex parts in single setups that would otherwise require multiple operations with handling damage risks. Precision capabilities reduce the scrap rates that consume both material and labor costs. When raw material prices remain elevated, these efficiency gains compound into significant competitive advantages.

Survey respondents across Texas manufacturing sectors expressed consistent themes: uncertainty about tariff impacts, pressure from pricing environments, and determination to invest through challenges rather than retreat. One machinery manufacturer reported November as their most profitable month of the year despite broader concerns, attributing success to increased business activity and new projects. Another noted that even modest interest rate decreases had provided confidence for expansion planning. The manufacturers achieving success share equipment capabilities enabling them to capture opportunity while competitors struggle with capacity constraints.

Capital expenditure intentions rose to 9.8 in November, with future investment expectations reaching 12.9—both readings indicating manufacturers plan equipment investments despite economic uncertainties. The forward-looking data suggests Texas manufacturers understand that competitive position depends on capability, not just cost management. Equipment investments made during periods of strong demand position shops to serve customers when conditions moderate, building relationships and reputation that persist through economic cycles.

Southwest Machine Technologies: Your Texas Fabrication Equipment Partner

Southwest Machine Technologies serves manufacturers across all 254 Texas counties with industry-leading machine tools, fabrication equipment, parts and accessories, and application support. Founded in 2022 and headquartered in Houston, our team brings over 125 years of combined experience to every customer relationship, with sales professionals who understand shop floor realities from direct experience.

Our Equipment Solutions Include:

  • Fabrication Machines – CMS waterjet cutting systems, Cosen saws, and precision fabrication equipment engineered for Texas manufacturing demands
  • Milling and Turning Centers – Smart Machine Tools, HNK, and Fuji Machine America machinery with FANUC controls and comprehensive service support

Ready to Expand Your Capabilities? Contact Southwest Machine Technologies to discuss how modern fabrication equipment can position your operation for Texas manufacturing’s continued growth.

Works Cited

“Texas Manufacturing Activity Accelerates, Though Employment Remains Flat.” Federal Reserve Bank of Dallas, Texas Manufacturing Outlook Survey, 24 Nov. 2025, www.dallasfed.org/research/surveys/tmos/2025/2511. Accessed 9 Dec. 2025.

“CNC (Computer Numerical Control) Machine Market Size, Share & Industry Analysis.” Fortune Business Insights, Nov. 2025, www.fortunebusinessinsights.com/industry-reports/computer-numerical-controls-cnc-machine-tools-market-101707. Accessed 9 Dec. 2025.

Related Articles


Open post Modern CNC machine tools operating in a Texas manufacturing facility, reflecting the precision and technology driving the $100B+ market.

CNC Machine Market Surges Past $100 Billion as Texas Shops Invest in Precision Equipment

Southwest Machine Technologies: Providing High Quality Products at Unmatched Value with Unrivaled Support

The global CNC machine tools market reached $25.53 billion in 2024 and is projected to expand to $44.64 billion by 2033, growing at a compound annual rate of 6.4 percent according to recent industry analysis. The United States commands approximately 32 percent of global market share, with over 38,000 CNC machines installed across industries and more than 2,100 manufacturers and suppliers supporting domestic production capabilities. For Texas fabrication shops competing in aerospace, automotive, energy, and precision manufacturing, this equipment investment surge represents both opportunity and competitive imperative.

The acceleration in CNC adoption reflects fundamental shifts in how manufacturers approach production challenges. Labor constraints affecting 60 percent of machine tool companies globally are pushing shops toward automation solutions that reduce operator intensity while maintaining output quality. Demand for 5-axis CNC machines—equipment capable of producing complex geometries in single setups—rose 24 percent year-over-year as manufacturers recognize that capability investments deliver returns traditional hiring strategies cannot match. The technology transition transforms shop floor economics by enabling smaller teams to accomplish work that previously required larger crews operating conventional equipment.

Texas manufacturers operate within this global equipment evolution while facing regional dynamics that amplify investment urgency. As detailed in Texas Manufacturers Face Equipment Modernization Pressure as Production Activity Accelerates, the state’s production index jumped 15 points in November 2025 while employment remained essentially flat—evidence that output gains increasingly depend on equipment capability rather than headcount expansion. Shops positioned with modern CNC systems capture the demand surge while competitors constrained by aging machinery watch opportunities pass to better-equipped rivals.

Precision Requirements Drive Technology Adoption

The automotive and aerospace sectors account for 58 percent of all CNC machine deployments in the United States, reflecting the precision requirements that define modern manufacturing. Engine components, transmission parts, turbine blades, and airframe structures demand tolerances measured in thousandths of an inch—specifications that only computer-controlled equipment can achieve consistently across production volumes. Texas manufacturers serving these sectors compete against suppliers worldwide, making equipment capability a threshold requirement rather than a competitive differentiator.

The Global Growth Insights CNC market analysis documents that 72 percent of CNC installations now integrate with IoT systems, enabling real-time monitoring, predictive maintenance, and data-driven process optimization. This connectivity transforms machine tools from standalone production assets into networked manufacturing systems generating continuous performance insights. Shops leveraging these capabilities identify inefficiencies, prevent downtime, and optimize throughput in ways that disconnected equipment cannot support.

The precision engineering segment is growing fastest within the CNC market, driven by medical device manufacturing, electronics production, and specialty component fabrication. These applications require micrometer-level accuracy that only advanced machine tools deliver. Texas manufacturers expanding into higher-value market segments find that equipment capability determines which contracts they can pursue. A shop limited to conventional machining cannot bid on work requiring five-axis positioning or sub-thousandth tolerances—the equipment gap becomes a revenue ceiling.

Multi-axis machining centers exemplify the capability evolution reshaping competitive dynamics. Traditional three-axis machines require multiple setups to produce complex parts, with each repositioning introducing potential for alignment errors and dimensional variation. Five-axis systems complete the same work in single setups, improving accuracy while dramatically reducing cycle times. The productivity differential compounds across production volumes, giving equipped shops substantial cost advantages on complex part families.

Workforce Dynamics Accelerate Equipment Investment

The U.S. Chamber of Commerce reports that Texas has 116 available workers for every 100 open jobs—a ratio indicating relative labor availability compared to states facing acute shortages. However, this aggregate figure masks severe constraints in skilled manufacturing trades. Texas currently has 554,000 open positions against 643,799 unemployed workers, but the mismatch between available skills and employer requirements leaves manufacturing positions chronically difficult to fill. CNC programming, machine operation, and equipment maintenance demand technical expertise that general labor availability statistics do not capture.

The skills gap drives equipment investment strategies that reduce dependence on hard-to-find expertise. Modern CNC systems incorporate conversational programming interfaces that simplify operation compared to traditional G-code entry. Automated tool changers eliminate manual setup complexity. Integrated quality monitoring catches errors before they generate scrap. Each feature reduces the skill threshold for productive equipment operation, enabling manufacturers to accomplish sophisticated work with the workforce actually available rather than the ideal workforce they cannot recruit.

Training economics further favor equipment investment over hiring expansion. Developing CNC programming proficiency through traditional pathways requires years of education and experience. Equipment with intuitive interfaces and built-in guidance accelerates this timeline, enabling manufacturers to develop internal talent faster than external recruitment allows. The equipment becomes a training platform that compounds its value by building workforce capabilities alongside production output.

Manufacturers adopting automation report that technology investments improve recruitment outcomes. Technical workers with CNC skills prefer employers operating current-generation equipment where their capabilities translate into interesting work and career development. Shops running decades-old machinery struggle to attract candidates who recognize that obsolete equipment limits their professional growth. Equipment modernization thus addresses both immediate productivity needs and longer-term talent pipeline requirements.

Texas Market Position and Competitive Dynamics

Texas manufacturing benefits from structural advantages that equipment investments amplify. Energy access, transportation infrastructure, regulatory environment, and market proximity create favorable operating conditions that attract manufacturing investment. The state’s labor force participation rate of 64.7 percent—above national average—indicates a working population actively engaged in employment. These fundamentals support manufacturing growth, but capturing opportunity requires production capabilities matching customer requirements.

The state’s diverse industrial base creates equipment demand across multiple categories. Waterjet cutting systems serve metal fabricators, aerospace suppliers, and architectural manufacturers requiring versatile material processing. Vertical and horizontal machining centers address automotive, energy, and general industrial applications. Turning centers support precision component production for oil and gas, medical device, and electronics customers. The regional diversity of applications that waterjet technology specifically addresses, examined in Waterjet Cutting Technology Gains Ground in Texas Metal Fabrication Operations, illustrates how equipment specialization enables manufacturers to pursue focused market segments.

Competition for Texas manufacturing work intensifies as reshoring initiatives bring production back from overseas and nearshoring trends relocate supply chains closer to end markets. Manufacturers winning this relocated work demonstrate capabilities—quality certifications, precision tolerances, delivery reliability—that equipment directly enables. A shop quoting reshored aerospace components must prove capability to produce parts meeting specifications that overseas suppliers struggled to achieve. Modern CNC equipment provides both the production capability and the process documentation supporting these capability claims.

The federal government’s emphasis on domestic manufacturing through infrastructure investments, defense spending, and industrial policy creates demand that equipped manufacturers can capture. Programs supporting semiconductor production, clean energy manufacturing, and defense supply chain resilience generate contracts flowing to manufacturers demonstrating appropriate capabilities. Equipment investments position shops to pursue these opportunities as they emerge rather than scrambling to build capability after contracts are awarded to better-prepared competitors.

Investment Decisions and Strategic Positioning

Equipment investment decisions involve tradeoffs between capability expansion and capital preservation that each manufacturer must navigate based on their specific circumstances. The shops achieving strongest returns typically identify specific capability gaps limiting their competitiveness, invest in equipment addressing those gaps, and leverage new capabilities to pursue work previously beyond their reach. This targeted approach delivers measurable returns rather than acquiring equipment hoping opportunity will follow.

The integration between equipment categories matters as much as individual machine capabilities. CNC machining centers, waterjet cutting systems, and fabrication equipment work together in production workflows where bottlenecks in any stage constrain overall throughput. Manufacturers optimizing their equipment mix achieve balanced capacity that maximizes utilization across all assets rather than leaving expensive machines idle while other processes catch up.

Service and support infrastructure influences equipment value beyond initial specifications. Machines require maintenance, repair, and application support throughout their operational lives. Manufacturers partnering with suppliers offering responsive service, parts availability, and technical expertise protect their equipment investments against downtime that erodes productivity gains. The equipment purchase decision extends beyond the machine itself to encompass the relationship supporting ongoing operations.

Southwest Machine Technologies: Your Texas CNC Equipment Partner

Southwest Machine Technologies serves manufacturers across all 254 Texas counties with industry-leading machine tools, fabrication equipment, and comprehensive service support. Our team’s 125+ years of combined experience includes extensive shop floor background—we understand manufacturing challenges from direct experience, not just sales presentations.

Our Equipment Solutions Include:

  • Fabrication Machines – CMS waterjet cutting systems and Cosen saws delivering precision fabrication capabilities for Texas manufacturers
  • Milling and Turning Centers – Smart Machine Tools, HNK, and Fuji Machine America equipment with FANUC controls and full service support

Ready to Expand Your Precision Capabilities? Contact Southwest Machine Technologies to discuss how CNC equipment investments can position your operation for growth in Texas manufacturing’s expanding market.

Works Cited

“CNC Machine Tools Market Size, Share, Growth, and Industry Analysis.” Global Growth Insights, Nov. 2025, www.globalgrowthinsights.com/market-reports/cnc-machine-tools-market-114969. Accessed 9 Dec. 2025.

Ferguson Melhorn, Stephanie, and Lindsay Burton. “Understanding America’s Labor Shortage: The Most Impacted States.” U.S. Chamber of Commerce, 16 Oct. 2025, www.uschamber.com/workforce/the-states-suffering-most-from-the-labor-shortage. Accessed 9 Dec. 2025.

Related Articles


Scroll to top